Do UFC fighters get health insurance? There is no single answer. Nevada requires promoters to carry at least $50,000 of medical coverage per licensed contestant for injuries sustained in the event, with no deductible. UFC announced a separate accident program in 2011. Current UFC terms are not published in the sources we could verify.
This guide is written for practice owners and billing managers, not for fans. It separates what primary sources confirm from what circulates online, then turns it into an intake and billing routine for practices that treat athletes.
Key takeaways
- Fighter coverage comes in layers: state event-injury rules, promotion policies and the athlete’s own plan.
- Nevada requires at least $50,000 of promoter-carried coverage per licensed contestant for event injuries, with no deductible.
- UFC’s 2011 announcement described an accident program that included training injuries; current terms were not found.
- No source we fetched supports a $50,000 UFC annual limit.
- Practices should confirm the injury circumstances and each payer’s position in writing before billing.
Do UFC fighters get health insurance? The verified answer
Fighter coverage is layered, and each layer comes from a different source. A state athletic commission can require the promoter to carry event-injury insurance. The promotion itself may add its own policies. The athlete may also hold personal health coverage. Which layer pays for a given injury depends on where and how the injury happened and on the policy wording.
This matters beyond sports news. A sports-medicine, orthopedic, urgent care or emergency practice that sees a combat-sports athlete has to decide which coverage to bill. This guide covers what primary sources confirm, what circulates online without a source, and how a billing team can handle the claim.
The original version of this post listed dollar limits, injury percentages and a pension bill without citing a source. Those figures have been removed. Only items we could check against a fetched primary source remain, and each one is dated.
What Nevada requires of promoters for event injuries
Nevada sets a written insurance floor for combat-sports events. Under Nevada Administrative Code 467.149, a promoter must carry insurance of at least $50,000 for each licensed contestant. The policy covers medical, surgical and hospital care for injuries the contestant sustains during the event.
| Item | What the rule says |
|---|---|
| Minimum for each licensed contestant | At least $50,000 |
| Care covered | Medical, surgical and hospital care for injuries sustained during the event |
| Deductible | The policy cannot require the contestant to pay a deductible for that care |
| If the contestant paid for the care | Insurance proceeds go to the contestant or the contestant’s beneficiaries as reimbursement |
| Amateur events | At least $25,000 for each unarmed combatant who is not a licensed contestant |
| If the promoter fails to provide coverage | The commission may order the promoter to reimburse the combatant up to the amount the insurance would have paid |
Source: Nevada Administrative Code 467.149, as published by Cornell Law School’s Legal Information Institute (page read October 2026; rule added 2000, amended 2009 and 2022).
Three points follow from the text. The $50,000 is a minimum, not a ceiling. It applies to injuries sustained during the event, not to training. And it is a Nevada rule. Other jurisdictions set their own requirements, and we did not review them for this post.
A state minimum is not a UFC annual limit
The old version of this post presented $50,000 as a yearly UFC cap on fighter medical costs. We found no primary source for a UFC-specific annual limit. The $50,000 figure we can source is Nevada’s per-contestant minimum for event injuries.
Federal law covers boxing, not MMA, as far as we verified
The federal Professional Boxing Safety Act, codified at 15 U.S.C. 6304, lists health insurance for each boxer to provide medical coverage for injuries sustained in the match. The section is written for professional boxing matches. We did not verify any equivalent federal requirement for mixed martial arts, so this post does not state one.
What UFC has said publicly, and what we could not confirm
In a May 9, 2011 announcement, Zuffa, LLC, then owner of the UFC brand, described a customized accident insurance program for nearly 350 UFC and Strikeforce athletes, described as independent contractors. The policy was underwritten by Houston Casualty Insurance Company. Zuffa said it paid 100 percent of the premiums and assigned an employee to handle and file claims.
The announcement said the program covered accidental injuries suffered in training and non-training incidents such as car accidents. It also listed 24-hour worldwide medical and life insurance, dental coverage and emergency medical evacuation. It said event coverage had always met or exceeded athletic commission requirements. It gave no dollar amounts, benefit maximums or deductibles.
That is a 2011 statement. Ownership, contracts and policies may have changed since, and we found no current official UFC page that lists today’s terms. A practice should treat the 2011 release as history, not as proof of what an athlete is covered for today.
The same caution applies to any article about fighter benefits, including this one. Policies change with contracts, ownership and state rules. The safest source for a specific athlete is the athlete’s own policy document or a written statement from the insurer.
| Claim in circulation | What the sources show | Status |
|---|---|---|
| Event injuries are covered by insurance | Nevada requires a promoter-carried policy of at least $50,000 per licensed contestant. UFC said in 2011 its event coverage met or exceeded commission requirements. | Supported for Nevada events; current UFC terms not confirmed |
| Training injuries are never covered | UFC’s 2011 release said its accident program covered training injuries. | Contradicted for 2011; current terms not confirmed |
| UFC has a $50,000 annual cap on medical costs | $50,000 is Nevada’s per-contestant minimum for event injuries. No UFC annual limit was found. | Not verified; removed |
| Fighters receive comprehensive health insurance | The 2011 release lists medical, life and dental benefits under an accident program. Current terms were not found. | Not verified for today |
| A California pension bill funded by $1 per ticket | No bill, number or status was identified. | Not verified; removed |
Sources: Nevada Administrative Code 467.149; UFC.com news release dated May 9, 2011. Rows marked removed were in the earlier version of this post.
Why this matters to a practice that treats athletes
A fighter who walks in with a fractured hand or a facial laceration raises the same first question as any patient: which coverage is billable for this visit? The difference is that more than one source may be in play, and the patient may not know which applies.
Documentation matters more than usual. Keep the date and place of injury, the coverage documents the patient provides, and the name and date of each payer contact in the account notes. If a payer later asks how the claim was routed, the record should answer it without a search through emails.
| Source | When it may apply | What to ask for |
|---|---|---|
| Event insurance carried by the promoter | The injury happened during a sanctioned event | Event date and location, promoter name, policy or claim contact, claim number |
| An accident policy offered through a promotion or team | The injury happened in training or outside an event, if such a policy exists | Policy document or card, claim form, who files claims for the athlete |
| The athlete’s own health plan | The injury is not covered elsewhere, or the plan is secondary | Insurance card, plan type, secondary coverage, referral or authorization rules |
| Self-pay arrangement | No coverage is confirmed, or the patient chooses to pay directly | Written estimate, payment terms, and a record that coverage was reviewed |
This table is an operations checklist, not a statement of which payer is primary. Payment order depends on plan terms and state law.
Our guides to coordination of benefits in medical billing and why coordination of benefits matters explain how a claim moves when more than one payer is involved. The same logic applies when one of the possible payers is an event or accident policy.
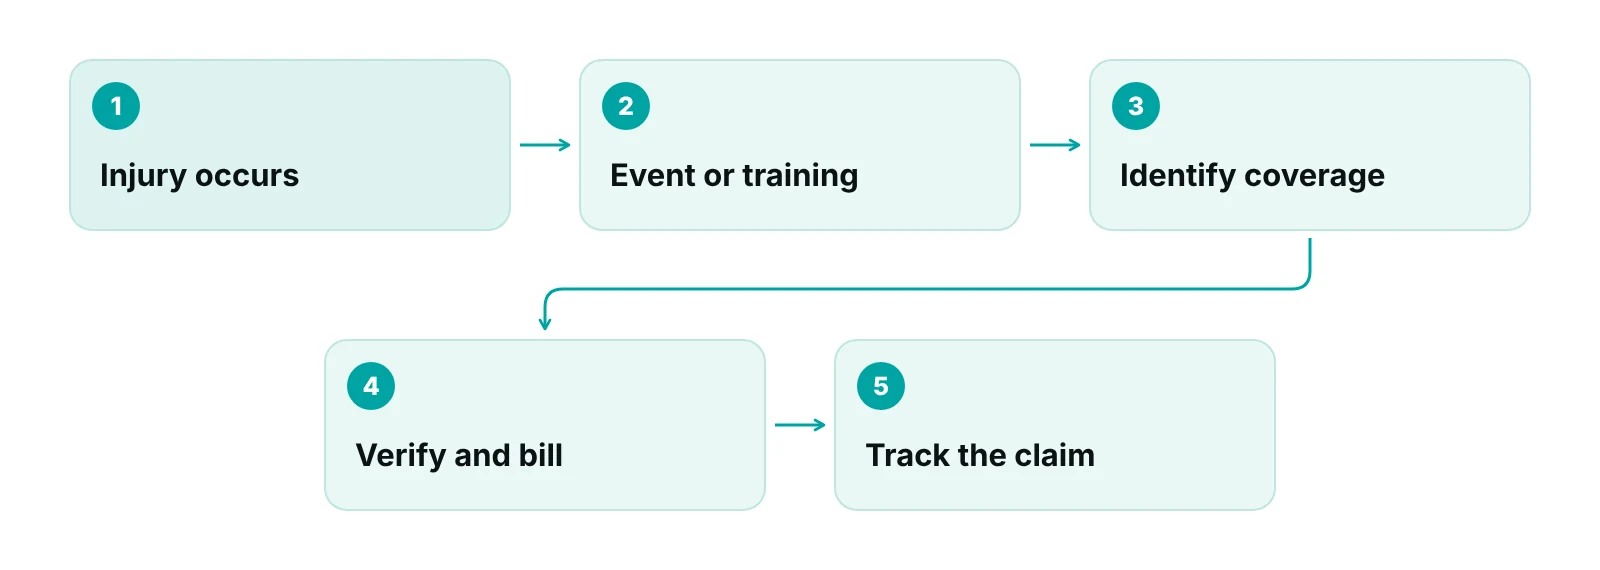
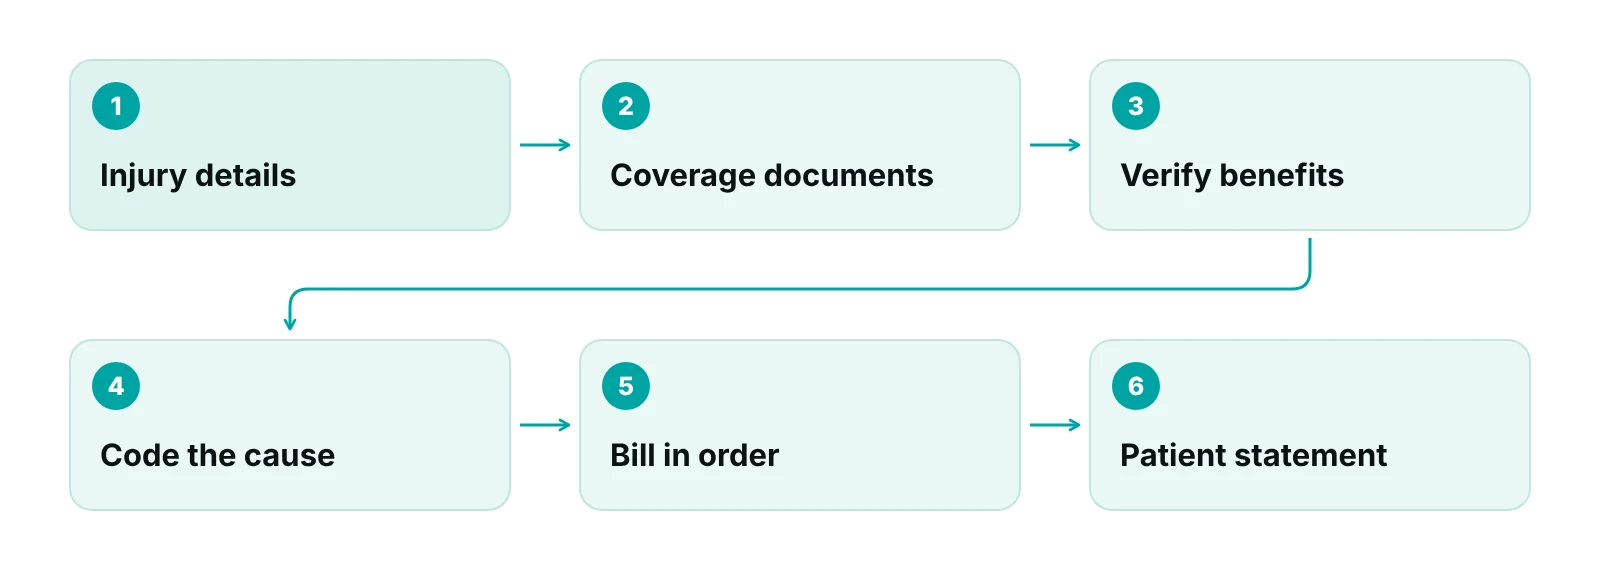
A workflow for event-injury and sports-injury claims
A written intake routine helps sports-medicine and orthopedic billing teams, because the injury circumstances decide which coverage to check. The goal is to settle the coverage question before the claim goes out, not after a denial.
- Ask how, when and where the injury happened. Record whether it was at an event, in training or elsewhere, and the date. Payers and promoters will ask the same questions.
- Collect every coverage document. Ask for the health plan card, any event or accident policy information and the claim contact. Do not assume a policy applies because the patient is a professional athlete.
- Verify benefits and rules with each payer. Confirm eligibility, referral and authorization requirements, and filing deadlines. Our insurance verification guide covers the steps.
- Document the cause on the claim. ICD-10-CM external cause codes (V, W, X and Y) capture the type of event, the location and the activity, and Highmark notes (February 2026) that they should never be sequenced as the principal or first-listed diagnosis. Your coder should apply them as secondary codes under the payer’s rules.
- Bill in the order the coverage rules require. Get each payer’s position in writing. Watch filing limits while you wait. See our state billing time limits guide for why this matters.
- Explain the balance clearly. Once payers respond, read each explanation of benefits and send a statement that matches it. Our guide to patient responsibility in medical billing covers what to include.
Claims that wait on another payer’s decision need an owner and a follow-up date. A practice management system that tracks claims by stage gives each one a visible status and a person responsible, so it does not sit in a general queue. If your team lacks time for this follow-up, a medical billing service can take it on.
“Settle which coverage applies before the claim goes out. A denial for the wrong payer costs more time than a phone call at intake.”
What not to assume
Do not tell a patient which plan must pay first, and do not assume a promoter or accident policy exists. Ask each payer, keep the answers on file, and send legal or coverage-order disputes to the patient’s insurer or an attorney.
Not sure how your team handles claims with more than one possible payer?
Our free practice audit reviews your intake questions, verification steps and claim follow-up, and shows where claims stall. Pricing for any service is quoted after the audit.
Mistakes that create rework
Most problems with unusual injury claims come from skipped intake questions, not from the rules themselves. These are the ones to watch for.
- Billing the health plan first when the patient says the injury happened at a sanctioned event, without asking for event coverage details.
- Telling a patient a policy has a certain limit based on an article or social post instead of the policy document.
- Leaving the date and place of injury out of the chart, so the claim cannot be matched to the right coverage later.
- Letting a claim sit with no owner while another payer decides, until a filing deadline passes.
- Sending the patient a statement before every payer has responded.
Our recommendations
- Ask the injury-circumstance question at scheduling. Add where and when the injury happened, and whether an event was involved, to your intake form so the right coverage is checked before the visit.
- Request the policy document, not a verbal summary. Coverage limits and exclusions are in the policy. Keep a copy or the payer’s written confirmation in the account.
- Verify each payer separately. Check eligibility, authorization and filing rules with every payer involved, and record the date and the name of the person you spoke with.
- Assign an owner and a follow-up date. Any claim waiting on another payer should show who is following up and by when, so deadlines are not missed.
- Send coverage-order questions to the right place. If the patient and payers disagree about who pays first, point the patient to the insurer or to legal counsel. Billing staff should not decide it.
A practice management system built around claims, not charts.
RCM Finder's portal tracks every claim by stage with an owner, flags underpayments against expected amounts and applies workflow rules to hold or advance claims. It is a claims system, not an EHR.
See how the RCM Finder portal works · Create a portal account
Disclosure: RCM Finder builds and sells this portal. It is a practice management system, not an EHR.
Bottom line
Do UFC fighters get health insurance? Sources confirm a layered system: state event-injury insurance rules such as Nevada’s $50,000 minimum, promotion policies whose current terms are not published, and the athlete’s own coverage. For a practice, the work is to confirm which coverage applies before billing. If denials from unclear coverage are costing your team time, see our denial management service or talk to our team.
Frequently asked questions
Do UFC fighters get health insurance?
Coverage comes in layers. Nevada requires promoters to carry at least $50,000 of medical, surgical and hospital coverage per licensed contestant for event injuries. UFC announced an accident program in 2011. Current UFC terms were not found in a verifiable source, so ask the athlete for the policy.
Does the UFC pay medical bills for fight injuries?
In Nevada the promoter must carry event-injury insurance with no deductible for the contestant. UFC stated in 2011 that its event coverage met or exceeded commission requirements. The amount and terms of any policy for a specific fight should be confirmed in writing.
Are training injuries covered?
UFC’s 2011 announcement said its accident program covered training injuries. We could not confirm whether that program or its terms are in place today. A practice should ask the athlete for current policy documents instead of relying on the 2011 statement.
Is $50,000 the UFC's annual medical limit?
No source we fetched says so. The $50,000 figure comes from Nevada’s rule as a minimum per licensed contestant for injuries sustained during an event. It is a floor set by the state, not a published UFC annual cap, and a policy may provide more than the minimum.
How should a practice bill an injury that may be covered by an event policy?
Collect the date and place of injury, the health plan card and any event or accident policy details. Verify with each payer, get coverage-order answers in writing, and have your coder apply external cause codes as secondary diagnoses under payer rules. Keep a note of every payer contact.
Does federal law require health insurance for MMA fighters?
The federal Professional Boxing Safety Act lists health insurance for each boxer for injuries sustained in the match. It is written for professional boxing. We did not verify an equivalent federal rule for MMA, and state rules differ.
Get your free practice audit
Tell us about your practice. We will contact you using the details you give.
- A review of your recent claims, denials and A/R aging
- Where your front desk and prior authorizations slow payment
- A prioritized fix list you keep, whether or not you hire us
Pricing is quoted after the audit, based on your volume and the services you choose. Prefer to talk? Call +1 (302) 556-2288.
Sources
- Nev. Admin. Code 467.149 Insurance coverage — Cornell Law School Legal Information Institute (Nevada Administrative Code) (2022)
- 15 U.S.C. 6304 Safety standards — Cornell Law School Legal Information Institute (U.S. Code) (2026)
- UFC announces accident insurance coverage for athletes — UFC.com (2011)
- Coding Corner: Understanding External Cause Codes — Highmark Provider Resource Center (2026)
Disclaimer: This post is general educational information about healthcare billing operations. It is not legal, insurance, coding or compliance advice. Coverage rules vary by state, event, policy and payer and can change. Confirm coverage with the payer or insurer and a qualified adviser before acting.