Unpaid medical bills usually move from patient statements to reminders, then to a payment plan, financial assistance review, an outside collection agency or a write-off. For patients the effects can include collection calls, credit reporting and delayed care. For practices they mean slower cash and extra work.
Most articles on this topic speak to patients. If you run a practice, the same question looks different: what happens to the balance, and what are we allowed and expected to do about it? This guide covers both sides, then the steps we recommend for handling patient balances.
It is education, not legal advice. Collection rules differ by state, payer and organization type.
Key takeaways
- Unpaid balances move through stages, and the best chance to resolve them is early, before an agency is involved.
- Credit reporting of medical debt changed in 2023-2025; the current limits come from the credit bureaus’ own policies, not a federal rule.
- Tax-exempt hospitals must offer financial assistance review before certain collection actions; independent practices should still adopt a written policy.
- Calls, letters and lawsuits are regulated. Ask counsel what applies to you and to any agency you hire.
- Clear statements, a fair payment plan and an owner for every balance prevent most write-offs.
What happens when a medical bill goes unpaid
A medical bill rarely jumps straight to a lawsuit. It usually moves through several stages over months, and what happens at each stage depends on the provider, the state and the size of the balance.
The scale is large. In KFF’s 2022 Health Care Debt Survey, 41% of U.S. adults said they currently had health care debt. KFF counted more than past-due bills: it included balances being paid off over time, credit card debt used for care and money borrowed from family. So the figure shows how many people carry a medical balance, not how many ignore their bills.
For a practice, the useful point is that most patients with debt did not plan for it. KFF found that 72% of those with debt pointed to a one-time or short-term medical expense. Many unpaid balances are people who are confused or stretched, not people who refuse to pay.
| Stage | What usually happens | What it means for the practice |
|---|---|---|
| Statement sent | Patient receives a bill after the insurer pays its part. | Statement clarity decides whether the patient understands the amount. |
| Reminders | Second and third statements, texts or calls. | Cheapest point to collect; keep a record of each contact. |
| Payment plan or financial assistance | Patient asks for time or help paying. | Resolves many balances; needs a written policy applied the same way each time. |
| Final notice | Letter stating what happens next and by when. | Check state rules and your own policy before sending. |
| Agency placement or write-off | Balance goes to an outside agency or is written off as bad debt. | Recovery is partial and the patient relationship often ends. |
Source: RCM Finder summary of common practice workflows; stages and timing vary by practice, state and payer.
What unpaid medical bills can do to a patient
The main consequences for patients are collection contact, possible credit-report entries, delayed care and, in some cases, legal action. Knowing them helps front-desk and billing staff talk about balances honestly.
Collections and care decisions
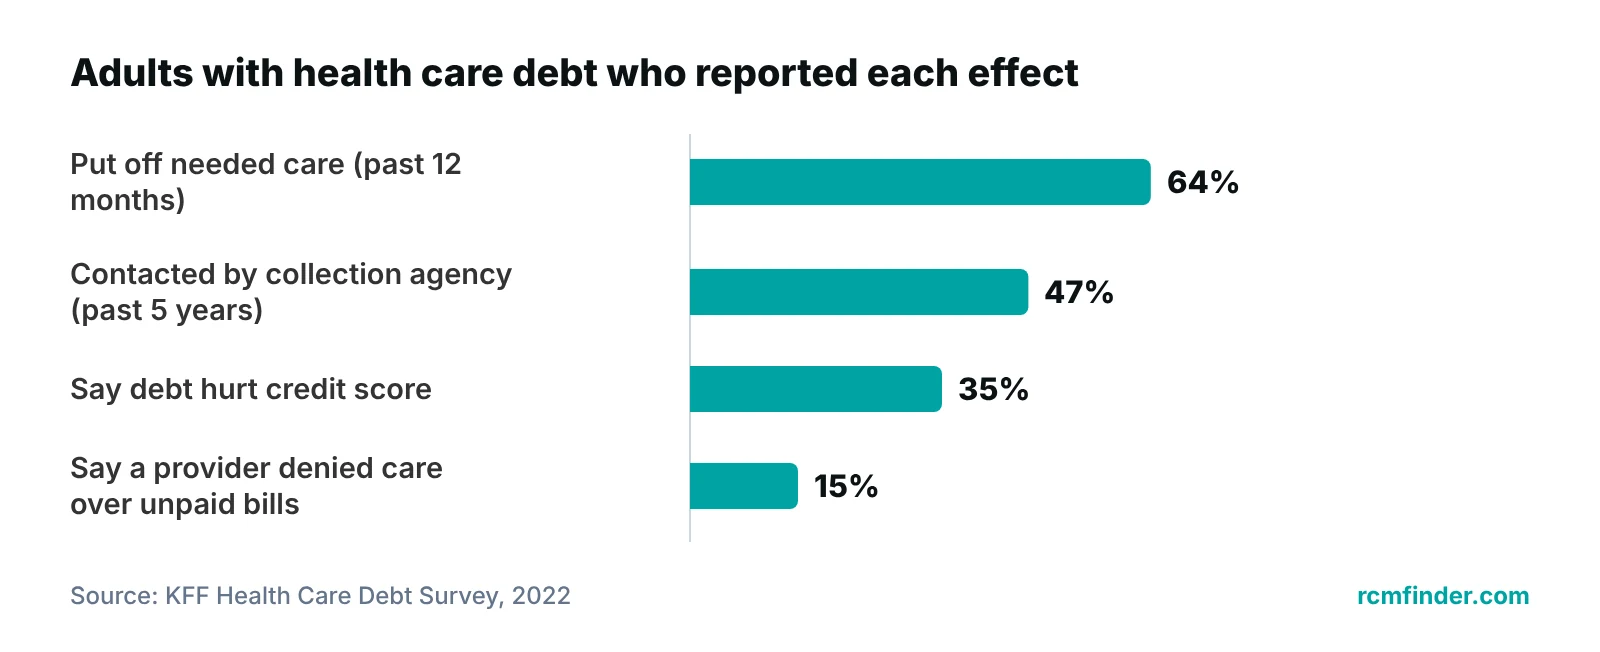
Among adults with health care debt in KFF’s 2022 survey, 47% said they or a household member had been contacted by a collection agency in the past five years. 64% said they or someone in the household had put off needed care because of cost in the past 12 months, and 15% said a provider had denied them care because of unpaid bills.
Emergency care is a separate rule
Under the federal EMTALA law, Medicare-participating hospitals that offer emergency services must screen and stabilize people with emergency conditions regardless of ability to pay, per CMS. That rule covers hospital emergency services, not routine office visits. A practice can have its own policy on scheduling patients with old balances, and that policy should be written and applied consistently.
Credit reports: what changed
Credit effects are the most misquoted part of this topic. According to Consumers’ Checkbook, a federal judge vacated the CFPB’s medical debt credit-reporting rule in mid-July 2025, so no federal rule currently bars medical debt from credit reports. Separately, Equifax, Experian and TransUnion announced in 2023 that they would not report medical debts under $500, would wait one year (up from six months) before reporting unpaid medical debt of $500 or more, and would stop reporting medical debt once it is repaid. Those are voluntary policies and can change.
Patients often ask what this means for their score. Our post on how medical bills affect credit scores covers that from the patient side. For your practice, the takeaway is simple: a balance can sit for a year or more before any credit effect, which leaves a long window to resolve it.
Lawsuits, liens and garnishment
Legal action is possible but not routine, and rules differ by state, so we do not quote national lawsuit or interest figures. Tax-exempt hospitals face limits on when such steps can start, covered below. Anyone facing a lawsuit should talk to a licensed attorney or legal aid office.
What unpaid patient balances do to a practice
Patient balances are slower and costlier to collect than insurer payments. Each statement, call and letter takes staff time, and the longer a balance ages, the less likely it is to be paid.
As deductibles and coinsurance shift cost to patients, the patient-responsibility share of each claim grows in importance. Our guide to patient responsibility in medical billing explains how that amount is calculated and why it often surprises patients.
Specialties with procedures or imaging can see larger single balances. In pain management, for example, a series of injections can leave a patient with a deductible and coinsurance amount they did not expect. We cover how that works on our pain management billing and RCM page.
- Cash flow: money you have earned is tied up in accounts receivable.
- Staff time: repeat calls and re-sent statements add cost for every balance still open.
- Patient relationship: aggressive follow-up can lose a patient who would have paid with a plan.
- Compliance risk: inconsistent policies, or collection steps taken too soon, can create legal exposure.
Many balances start as a front-end problem: unclear estimates, missed eligibility details or an insurer denial passed to the patient. If you are seeing unpaid balances that began as denied claims, see our overview of medical billing denial management.
The rules that shape how you collect
Several federal rules touch patient collections, and which ones apply depends on your organization type. The table lists the ones that come up most often. Ask your attorney which apply to you and your agency.
| Rule or source | Who it covers | What it says |
|---|---|---|
| IRS Section 501(r)(6) | Hospital organizations that must follow the financial assistance rules | Before extraordinary collection actions such as credit reporting, liens or lawsuits, the hospital must make reasonable efforts to check financial assistance eligibility. That includes waiting at least 120 days from the first post-discharge bill, and written notice with a deadline no earlier than 30 days out. |
| Regulation F, 12 CFR 1006.14 | Debt collectors | Calls are presumed to violate the repeated-calls ban if placed more than seven times in seven consecutive days, or within seven days after a phone conversation about that debt. |
| EMTALA (CMS) | Medicare-participating hospitals offering emergency services | Screening and stabilization for emergency conditions regardless of ability to pay. |
| OIG guidance on copayment waivers | Providers billing Medicare | OIG has long voiced concern about arrangements that routinely waive Medicare copayments. |
Sources: IRS (Section 501(r)(6) page); CFPB Regulation F via eCFR (12 CFR 1006.14); CMS (EMTALA); HHS OIG statement to the Practicing Physicians Advisory Council (1999), which cites the 1994 Special Fraud Alert.
A useful benchmark: Section 501(r)
The IRS describes extraordinary collection actions as selling the debt, reporting adverse information to credit agencies, deferring or denying medically necessary care because of past bills, and legal or judicial processes such as liens or lawsuits. It also sets an application period of 240 days from the first post-discharge statement. Your practice may not be covered, but its sequence is a sound model: tell the patient help exists, give time to apply, then escalate.
Do not waive copays as a habit
Forgiving a patient’s cost-sharing as a marketing tool or by default is not the same as hardship help. HHS OIG has said it has repeatedly voiced concern about arrangements that routinely waive Medicare copayments, and cites a 1994 Special Fraud Alert. Document any hardship adjustment case by case, in line with a written policy, and confirm the approach with compliance counsel.
Third-party agencies
When you place accounts with an agency, ask what contact limits, state licenses and complaint handling it follows, and how it protects patient information. HIPAA still applies: share only the minimum needed, and put a Business Associate Agreement in place where the agency handles protected health information.
A fair collection workflow for patient balances
A fair workflow gives every balance a clear path, an owner and a date. Patients pay faster when they understand the bill and know their options.
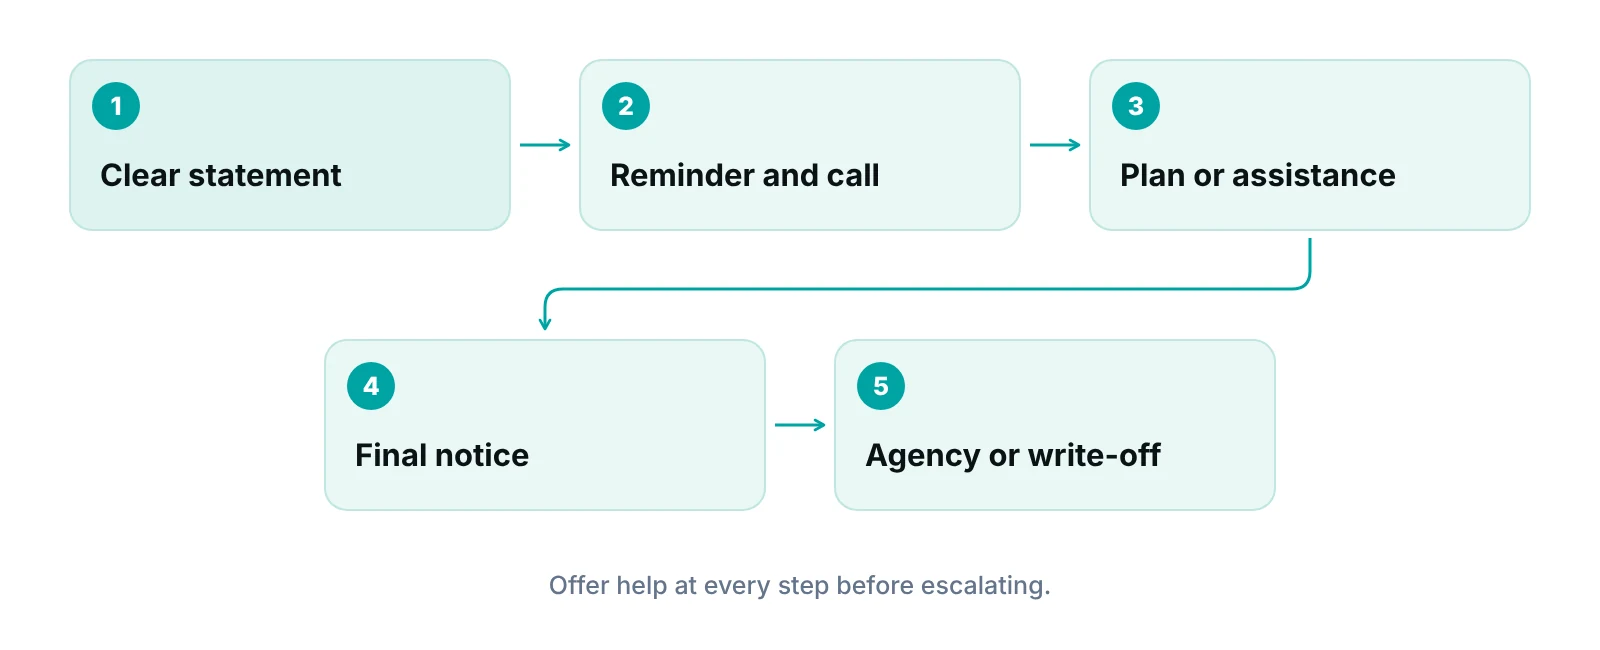
- Send a clear statement quickly. State what the insurer paid, what the patient owes and how to pay or ask for help. See our guide to patient-friendly billing statements.
- Contact the patient in more than one way. Use mail, phone and text where the patient has agreed. Log every contact, and respect call frequency limits.
- Offer a payment plan or assistance review. Many patients can pay over time. Set terms in writing; our post on patient payment plans covers the options.
- Send a final notice before escalation. Say what will happen and when. Check your state’s requirements and your written policy first.
- Decide: agency, internal follow-up or write-off. Weigh the balance size, the patient’s situation and the cost of pursuit, then document the decision.
See where your patient balances stall
A free practice audit reviews how balances move through your statements, follow-up and write-offs, and shows where cash is slowing down.
Handling unpaid balances: in-house, outsourced or agency
The right model depends on volume, staff capacity and how much of your A/R is patient-owed. Most practices combine approaches.
| Option | Works best when | Watch for |
|---|---|---|
| In-house front desk and billing team | Low balance volume and a team with time for follow-up | Follow-up competes with check-in and claim work, so balances age. |
| Outsourced A/R follow-up | Balances and claim follow-up both pile up | Ask who contacts patients, what script is used and how often. |
| Payment plans with automated reminders | Many small and mid-size balances | Terms must be written down and applied consistently. |
| Third-party collection agency | Late-stage balances where earlier steps failed | Agency conduct reflects on you; confirm licensing, call limits and HIPAA terms. |
Source: RCM Finder operational guidance; no outcome figures are implied.
If balances are piling up, an A/R management service can take over the follow-up so your front desk keeps its focus. For the full picture of how balances relate to the rest of your cycle, see strategies for improving patient collections.
A practice management system that tracks claims by stage also helps, because every balance has an owner and a visible status. It is not an EHR.
“Most unpaid balances are not a collections problem. They are a communication problem that shows up late.”
Our recommendations
- Write a financial assistance and payment policy. Put in writing who qualifies for help, what documents you ask for and what payment plans you offer. Apply it the same way every time.
- Quote patient cost before the visit. Many unpaid balances come from surprise. Explain deductibles and coinsurance at scheduling and check-in.
- Give every open balance an owner and a date. If nobody owns a balance, it ages. Track balances by stage, the way you track claims.
- Follow up early and in more than one way. Contact patients while the visit is fresh, and keep a log. Respect call frequency limits.
- Escalate slowly and document why. Offer help before an agency, and record each decision. Check state rules before legal steps.
- Review agency terms with counsel. Confirm licensing, contact limits, complaint handling and a Business Associate Agreement before sending accounts out.
Track every patient balance by stage with an owner.
The RCM Finder portal is a claim-centred practice management system with claim tracking by stage, workflow rules, reporting dashboards and an audit log. It is not an EHR.
See how the RCM Finder portal works · Create a portal account
Disclosure: RCM Finder builds and sells this portal. It is a practice management system, not an EHR.
Bottom line
Unpaid medical bills are a stage-by-stage process, and the earliest stages are where you have the most control. Clear statements, early contact, fair payment options and documented policies resolve most balances before collections. If follow-up is stretching your team, our medical billing services and revenue calculator are good next steps, or you can request a free practice audit.
Frequently asked questions
What happens if you don’t pay a medical bill?
The provider usually sends reminders, then may offer a payment plan or financial assistance. If the balance stays open, it can be placed with a collection agency, and legal action is possible in some cases. Timing and rules vary by state and provider, so patients should contact the billing office early.
How long before an unpaid medical bill hits your credit report?
There is no single federal timeline. Under policies announced in 2023, Equifax, Experian and TransUnion wait one year before reporting unpaid medical debt of $500 or more and do not report amounts under $500, as reported by Consumers’ Checkbook. Those are voluntary and may change, so check current policy.
Can a medical practice send patients to collections?
Generally yes, subject to state law, your contracts and your own policy. Tax-exempt hospitals must follow Section 501(r) steps first, including financial assistance review. Independent practices should still send clear statements, offer a payment plan and consult counsel before agency placement.
Can a hospital refuse emergency care because of unpaid bills?
No. Under EMTALA, Medicare-participating hospitals that offer emergency services must screen and stabilize emergency conditions regardless of ability to pay, per CMS. This applies to emergency services; it does not govern routine office visits or non-emergency care.
Should a practice waive copayments for patients who can’t pay?
Do not waive them routinely. HHS OIG has voiced long-standing concern about arrangements that routinely waive Medicare copayments. Hardship help can be appropriate when documented case by case under a written policy, but confirm your approach with compliance counsel.
How can a practice reduce unpaid patient balances?
Explain patient costs before the visit, send clear statements quickly, contact patients in more than one way, and offer written payment plans. Give each open balance an owner and track it by stage so none ages unnoticed. See our patient collections guide for details.
Get your free practice audit
Tell us about your practice. We will contact you using the details you give.
- A review of your recent claims, denials and A/R aging
- Where your front desk and prior authorizations slow payment
- A prioritized fix list you keep, whether or not you hire us
Pricing is quoted after the audit, based on your volume and the services you choose. Prefer to talk? Call +1 (302) 556-2288.
Sources
- KFF Health Care Debt Survey — KFF (2022)
- Billing and collections – Section 501(r)(6) — IRS (current)
- Emergency Medical Treatment & Labor Act (EMTALA) — CMS (current)
- 12 CFR 1006.14 Harassing, oppressive, or abusive conduct — eCFR / CFPB (current)
- Federal Judge Kills CFPB Rule that Banned Medical Debt in Credit Reports — Consumers’ Checkbook (2025)
- Statement of Kevin G. McAnaney to the Practicing Physicians Advisory Council — HHS OIG (1999)
Disclaimer: This article is educational and is not legal, tax, coding or compliance advice. Collection, credit-reporting and financial-assistance rules vary by state, payer and organization type. Speak with a qualified attorney or compliance adviser about your situation.